EXECUTIVE SUMMARY
India's non-life insurers wrote Gross Direct Premium Income (GDPI) of US$ 38.00 billion in FY26, while life insurers' new business premiums reached US$ 16.70 billion in the year to July 2026. Insurance penetration held steady at 3.70% of GDP in FY25, with density rising to US$ 97 per capita.

Non-Life GDPI (FY26)
US$ 38.00B

Life New Business Premium (FY27 YTD)
US$ 16.70B

Insurance Penetration (FY25)
3.70%

Insurance Density (FY25)
US$ 97
Introduction
India's insurance industry spans life insurance and non-life (general) insurance, covering motor, health, fire, marine, crop and specialised risk products, alongside a growing reinsurance segment. The Insurance Regulatory and Development Authority of India (IRDAI), established in 1999, regulates the sector under the Ministry of Finance, overseeing 74 registered insurers as of March 31, 2025, including 26 life insurers, 25 general insurers, 8 standalone health insurers, 13 reinsurers, and 2 specialised insurers.
The sector has evolved from state monopoly, with life insurance nationalised into the Life Insurance Corporation of India (LIC) in 1956 and non-life business nationalised into the General Insurance Corporation of India (GIC) in 1972, through liberalisation in 1999-2000 that opened the market to private players. Foreign investment limits have since risen from 26% in 2014 to 49%, then 74%, before the government enabled full foreign ownership under 2025 reforms, reflecting sustained policy support for the industry.
India's insurance sector has grown at a CAGR of about 17% over the past two decades, driven by rising incomes, expanding distribution networks, deeper private-sector participation and improving operational efficiency. Regulatory reforms, technological adoption and growing financial inclusion continue to position the industry as a key pillar of India's expanding financial ecosystem.
MARKET SIZE AND GROWTH
- Non-life insurers' GDPI rose from Rs. 2,89,673 crore (US$ 35.00 billion) in FY24 to Rs. 3,07,611 crore (US$ 36.40 billion) in FY25 and Rs. 3,35,918 crore (US$ 38.00 billion) in FY26, a 9.20% year-on-year increase. ICRA projects the general insurance sector to grow 8.70% in FY26, with premium income of Rs. 3.21-3.24 lakh crore (US$ 37.60-37.90 billion), and a further 10.90% rise in FY27.
- Life insurers' new business premiums reached Rs. 1,55,625.40 crore (US$ 16.70 billion) in the year to July 2026, up 17.45% year-on-year, with LIC contributing 60.11% (Rs. 93,542.49 crore, US$ 10.04 billion) and private insurers 39.89% (Rs. 62,082.91 crore, US$ 6.66 billion). Renewal premiums rose from US$ 54.50 billion in FY24 to US$ 57.70 billion in FY25.
- Insurance penetration held at 3.70% of GDP in FY25 (life 2.70%, non-life 1.00%), while density rose from US$ 95 in FY24 to US$ 97 in FY25.
- India ranked as the 10th-largest insurance market globally by premium volume in 2024-25, and the Insurance Regulatory and Development Authority of India (IRDAI) projects it will become the sixth-largest within a decade, leapfrogging Germany, Canada, Italy and South Korea.
KEY SEGMENTS
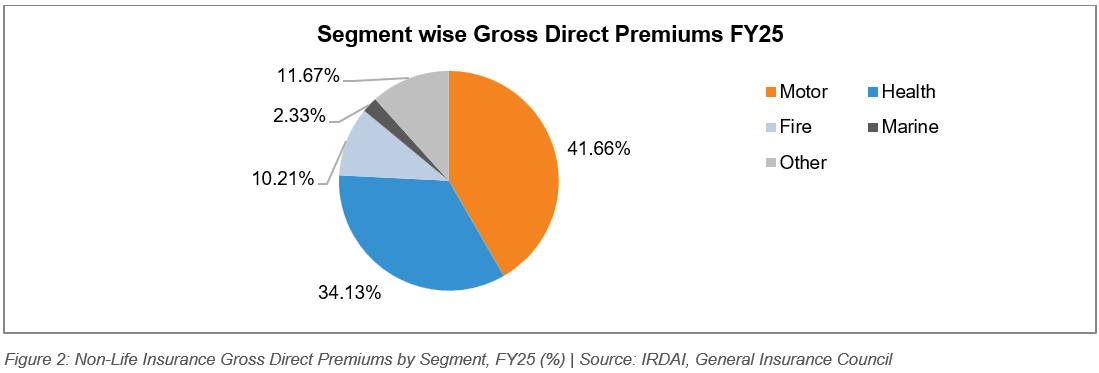
INVESTMENTS AND FDI
- Insurance attracted Foreign Direct Investment (FDI) equity inflows of Rs. 3,945.07 crore (US$ 429.81 million) during January-March 2026, about 3.92% of total sectoral FDI inflows.
- In February 2026, South Korean insurers including Samsung Fire & Marine Insurance, Mirae Asset Financial Group and Hyundai Marine & Fire Insurance explored entry into India's insurance market.
- Nine insurers, including HDFC Ergo and SBI General, submitted Initial Public Offering (IPO) plans to IRDAI in February 2025, and at least six Indian reinsurance companies plan to launch IPOs, selling 10-15% stakes to raise capital.
- IRDAI proposed raising insurers' combined investment limit in REITs and InvITs to 6% on May 21, 2026, and the Union Cabinet approved the Bharat Maritime Insurance Pool with a sovereign guarantee of Rs. 12,980 crore (US$ 1.47 billion) on April 18, 2026.
GOVERNMENT INITIATIVES
- Sabka Bima Sabki Raksha (Amendment of Insurance Laws) Bill, 2025: Passed in December 2025, enabling up to 100% FDI in insurance companies, reducing reinsurance entry barriers and strengthening regulatory oversight.
- Ayushman Bharat PMJAY SEHAT Scheme: The world's largest government-financed health insurance scheme, offering Rs. 5,00,000 (US$ 6,074) cover per family per year for secondary and tertiary care hospitalisation.
- Pradhan Mantri Suraksha Bima Yojana (PMSBY): An accident insurance scheme offering Rs. 2 lakh (US$ 2,142) cover at Rs. 20 (US$ 0.21) annual premium; enrolled over 58.09 crore people, with Rs. 3,667.52 crore (US$ 392.80 million) in claims disbursed as of April 29, 2026.
- Pradhan Mantri Jeevan Jyoti Bima Yojana (PMJJBY): Recorded over 27.43 crore cumulative enrolments, with Rs. 21,512.50 crore (US$ 2.40 billion) in claims disbursed to more than 10.75 lakh beneficiaries as of April 29, 2026.
- GST Exemption: 18% GST removed on individual life and health insurance policies, including family floater plans, effective September 22, 2025.
- National Export Insurance Account (NEIA): Supports the insurance cover provided by Export Credit Guarantee Corporation of India Ltd for project exports, helping Indian exporters compete abroad.
- Foreign Exchange Management Act (FEMA) Amendment: Amended in April 2022, paving the way for up to 20% FDI in LIC's Initial Public Offering (IPO).
- Pradhan Mantri Fasal Bima Yojana (PMFBY): Claims worth Rs. 1.96 lakh crore (US$ 22.20 billion) disbursed to about 24.31 crore farmers up to December 31, 2025, backed by escrow-based premium deposits and an automatic 12% penalty for delayed claims.
DRIVERS AND OPPORTUNITIES
- Rising incomes - India's GDP per capita rose from US$ 1,913 in 2020 to US$ 2,759 in 2026, channelling higher household savings into insurance and pension instruments.
- Digital transformation - Robotic Process Automation, Artificial Intelligence (AI) and Internet of Things (IoT) devices such as wearables and connected cars are reshaping risk assessment, with India's IoT insurance market projected to reach Rs. 1,83,120 crore (US$ 21.40 billion) by 2033, growing nearly 55% annually.
- Distribution expansion - Bancassurance, Point-of-Sale Person (PoSP) networks and digital aggregator platforms, including IRDAI's Bima Sugam marketplace, are widening reach into underserved segments.
- Financial inclusion - Tier-III cities and smaller towns contributed 62% of India's new insurance premiums in FY25, and the life insurance agent count grew 7.88% to around 3.03 million, adding over 1.10 million new agents.
- Regulatory push - IRDAI's “Insurance for All by 2047” vision and the removal of prior approval requirements for new retail health insurance products are accelerating product innovation.
- Fastest-growing major market - India's insurance market is projected to be the fastest-growing among major global markets, expanding at 6.90% annually during 2026-2030.
STRATEGIES
- Distribution partnerships - ICICI Lombard has built bancassurance and NBFC partnerships spanning over 200 financial entities, including banks, non-banking financial companies, housing finance firms and microfinance institutions, to deepen insurance penetration through integrated lending channels.
- Branch and talent expansion - SBI Life is widening its physical branch network in emerging regions while running large-scale student engagement programmes to build a distribution and talent pipeline aligned with “Insurance for All by 2047.”
- Digital distribution - HDFC Life is expanding corporate agency partnerships with fintech and non-banking platforms to embed insurance products within digital consumer journeys and reach underserved customers.
M&A
- Zurich Insurance Company will invest about Rs. 4,051 crore (US$ 487 million) for a 51% stake in Kotak General Insurance, with plans to acquire a further 19% stake within three years.
- Bajaj Group secured approval in March 2025 to acquire Allianz SE's 26% stake in their joint life and general insurance ventures for Rs. 24,180 crore (US$ 2.83 billion).
- The Mumbai National Company Law Tribunal (NCLT) approved the merger of Exide Life Insurance with HDFC Life.
- On July 24, 2026, BNP Paribas Cardif agreed to acquire an approximately 26% stake in IndiaFirst Life Insurance Company from Warburg Pincus, subject to regulatory approvals.
TRENDS
- Shift to non-linked products - Non-linked products accounted for nearly 82% of life insurance premiums (Rs. 7,26,634 crore, US$ 85.90 billion) in FY25, against 18% for linked products (Rs. 1,59,138 crore, US$ 18.80 billion), reflecting continued preference for traditional protection and guaranteed-return plans.
- Digital-first servicing - LIC launched the 'MyLIC' and 'Super Sales Saathi' mobile applications in April 2026 for paperless policy servicing, while IRDAI's Bima Sugam marketplace, launched in September 2025, lets policyholders compare, buy and manage policies on a single platform.
- Price transparency - Online insurance aggregator PolicyX.com launched India's first insurance price index, allowing consumers to track premium price trends.
- Faster product approvals - Insurers can now launch new retail health insurance products without prior IRDAI approval, a flexibility earlier limited to group insurance products.
RECENT DEVELOPMENTS
- July 24, 2026 : BNP Paribas Cardif agreed to acquire an approximately 26% stake in IndiaFirst Life Insurance Company from Warburg Pincus.
- June 29, 2026 : HDFC Life partnered with Tata Fintech to offer its protection and investment solutions on the Tata Neu app.
- May 26, 2026 : Shriram General Insurance partnered with Piramal Finance to expand insurance access across 700-plus branches covering 26 states and over 13,000 pin codes.
- April 15, 2026 : LIC launched the 'MyLIC' and 'Super Sales Saathi' mobile applications to strengthen paperless policy servicing and AI-enabled sales support.
- March 17, 2026 : SBI Life Insurance opened a new branch in Hyderabad, expanding its Telangana network to 59 branches.
- December 4, 2025 : ICICI Lombard partnered with Vastu Housing Finance to distribute digital insurance products to affordable housing customers across multiple states.
FAQs
It comprises life insurance and general (non-life) insurance, covering motor, health, fire, marine, crop and specialised products, regulated by the Insurance Regulatory and Development Authority of India (IRDAI).
Growth is driven by rising incomes, regulatory reforms including foreign investment liberalisation and GST relief, expanding digital distribution, and a strong push toward financial inclusion.
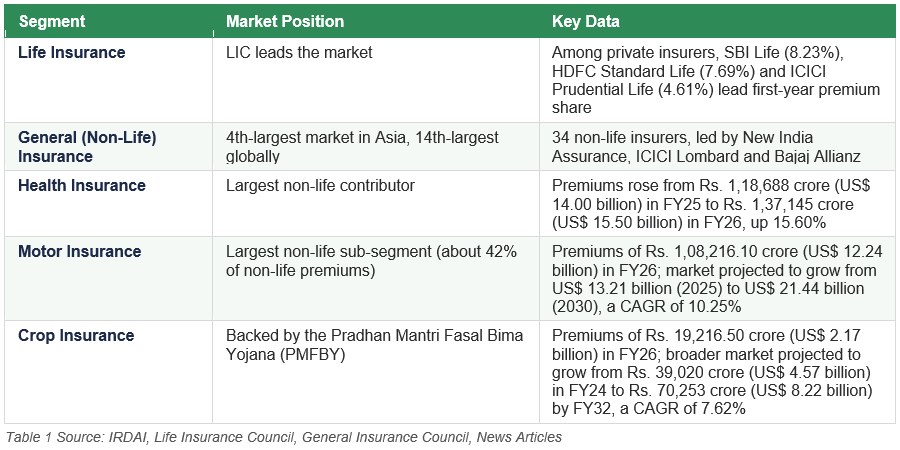
The major segments are life insurance, and general insurance comprising motor, health, fire, marine and crop insurance, alongside a growing reinsurance segment.
Key drivers include rising GDP per capita, expanding bancassurance and digital distribution networks, growing contribution from tier-III cities, and supportive regulatory reforms.
Artificial Intelligence, automation and IoT devices are enabling personalised risk assessment, while platforms like Bima Sugam and mobile apps such as MyLIC are simplifying policy purchase and servicing.
Support includes the Sabka Bima Sabki Raksha Bill's foreign investment liberalisation, GST exemptions on individual life and health policies, and schemes such as PMJAY, PMSBY, PMJJBY and PMFBY.
Opportunities include full foreign ownership under the automatic route, a growing IPO pipeline among insurers and reinsurers, and rising M&A activity in life and general insurance.
Penetration is improving through expanding bancassurance and PoSP networks, rising tier-III city demand, GST-driven premium reductions, and government-backed social security schemes.
India is projected to become the sixth-largest insurance market globally within a decade, with life insurance premiums set to reach US$ 317.98 billion by FY31 and the industry ranked among the fastest-growing major global markets.
Related News
MORE

IBEF Campaigns
MORE

Case Studies
MOREHow Indian Pharmaceutical Companies Are Strengthening Their Position in Global Markets
India has become a key player in the pharmaceutical industry of the world, which can be described in terms of the following factors: large-scale manuf...
Containerisation: Transforming India's Maritime Trade
Despite other modes of transportation, the maritime shipping mode is the backbone of international trade. The concept of containerisation has revoluti...
India’s Growing Senior Care Needs: New Businesses and Services
The current state of India is characterised by the process of demographic transition with gradual growth of the proportion of senior citizens within t...
IBEF BLOG
MORE
Investment Opportunities in India: Sectors With Strong Growth Potential
India has emerged as a potential investment destination owing to its econom...
Why Smaller Indian Cities Are Becoming New Destinations for Property Development
The Indian property development landscape is witnessing a broadening of opp...
India's Blue Economy: Untapped Potential in Ports, Fisheries and Ocean Resources
The maritime space of India, which comprises the coastline, island areas, a...
Partners